
Insurance Agent vs. Real Estate Agent — Which Career Pays More?
Insurance agent vs real estate agent: compare income, startup costs, work-life balance, and long-term earnings. See which career wins.
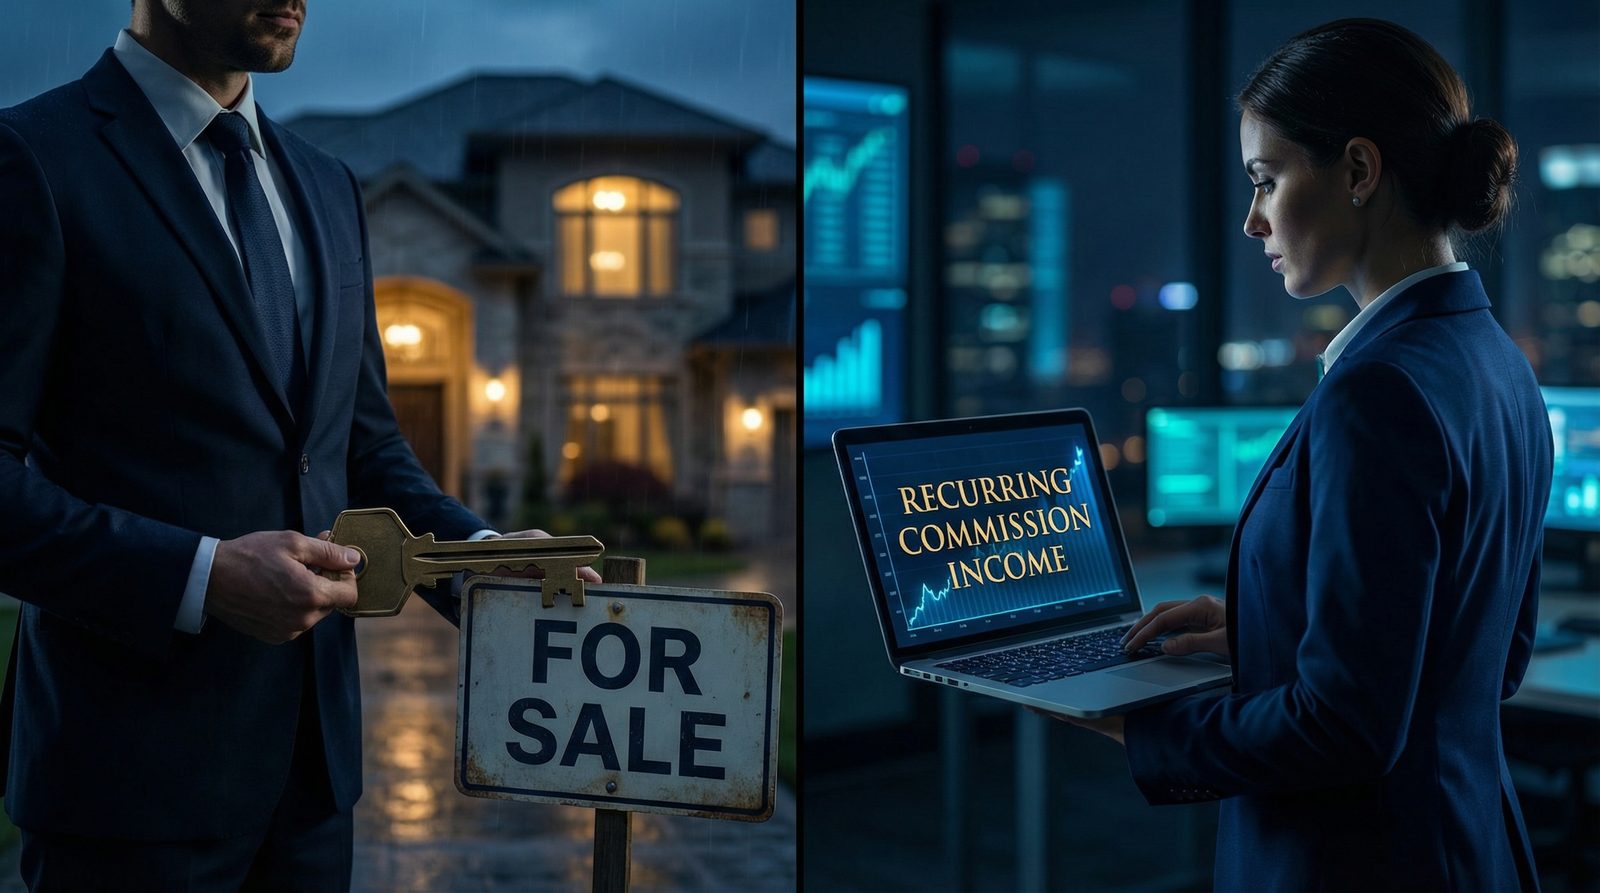
Real estate and life insurance attract the same kind of person: someone who wants to be paid for results, set their own schedule and work with people. Both are commission careers that start with a state license. They differ in how long licensing takes, what it costs to operate and, most of all, how the money arrives. Here is a side-by-side look.
Licensing: Similar Steps, Different Hours
Both careers need a state license, an exam and a background check. Real estate also requires a pre-licensing course, and it usually takes longer: 63 hours in Florida, 135 hours (three college-level courses) in California and 180 hours in Texas, for example. Life insurance pre-licensing requirements are usually shorter, and some states have none.
Who You Work Under
A new real estate agent must work under a sponsoring broker, who supervises the agent and takes a share of each commission. A life insurance agent contracts with insurance carriers, usually through an agency or marketing organization that provides contracts, training and support. Captive insurance agents work for a single company instead.
Startup and Ongoing Costs
Real estate agents commonly pay for MLS access, association dues if they join a Realtor association, a lockbox key, signs, marketing and sometimes desk or technology fees to their broker. Many carry errors and omissions insurance too.
A life insurance agent's main costs are licensing fees, errors and omissions coverage where required and, depending on the agency, leads and software. There are no listings to market and no open houses to staff.
How the Money Arrives
A real estate commission is paid at closing, after the brokerage takes its split. A purchase often takes a month or more to close after the contract is signed, and deals can fall through. Income depends heavily on the housing market: interest rates, prices and inventory.
A life insurance commission is paid when the policy is issued, often partly as an advance. If the policy cancels in its first months, the advance can be charged back. After the first year, many policies pay smaller renewal commissions while the client keeps paying, something a home sale never does. Our passive income guide explains renewals.
Side by Side
Which Pays More?
Neither has a cap, and both have wide ranges. The Bureau of Labor Statistics reported a median annual wage of $62,280 for insurance sales agents in May 2025. In both fields, the people at the top usually got there through years of steady work and referrals, and nothing is guaranteed. The real difference is the shape of the income: real estate pays in larger, less frequent checks, while life insurance pays in smaller, more frequent ones with renewals underneath.
See our income guide for how life insurance commissions work by product.
Can You Do Both?
Some people hold both licenses, and the two fit together: home buyers often need life insurance to protect a new mortgage. In practice, most agents find one career takes all their time early on, so pick a primary focus and check your brokerage's rules on outside business.
Choosing Life Insurance With Maxout
Maxout Insurance has no startup cost to join. Agents work remotely and get leads to work, training and Maxout CRM, with AI texting, a power dialer and automatic follow-up, plus term life, IUL, annuities and final expense from 30+ A-rated carriers.
Ready to Start Your New Career?
Join Maxout Insurance today. No experience needed, no startup cost, full training and leads provided.
Apply Now — It's FreeRelated Articles
More career guides
Frequently Asked Questions
Which pays more: insurance or real estate?
Both are commission careers with no cap and wide ranges. The Bureau of Labor Statistics reported a median annual wage of $62,280 for insurance sales agents in May 2025. Insurance adds renewal commissions while policies stay in force; real estate pays larger checks less often.
Which license is faster to get?
Usually life insurance. Real estate pre-licensing often runs 60 to 180 hours depending on the state, while life insurance requirements are usually shorter and some states have none.
Which has lower startup costs?
Usually life insurance. Real estate agents often pay MLS and association dues, a lockbox, signs and broker fees. Life agents mainly pay licensing fees and, depending on the agency, leads and software.
Can I do both?
Yes. Some agents hold both licenses, and home buyers often need life insurance for a new mortgage. Most find it works best to focus on one career first.